

Domain: INSURANCE
Topic: Umbrella Insurance
Read time: ~4 min
By: Andrew Abbott
EDUCATIONAL CONTENT ONLY -- The content in this newsletter is for educational and informational purposes only. It is not investment advice, tax advice, or a recommendation to buy, sell, or hold any security or financial product. Physicians Invest is not a registered investment advisor. Consult with qualified professionals regarding your specific financial situation.
The 2-Minute Version
Umbrella insurance is personal liability coverage that starts once your auto and home policies max out.
It does not cover malpractice. It covers claims caused from things in your personal life: the car, the pool, the dog, the rental property.
Most attendings should carry $1M-$5M of coverage, since physician income and visible assets make them a common lawsuit target. About $400/year buys the first million; each additional million runs ~$75.
The Dollar Math
About $400/year buys $1M of protection for the lawsuit tail if your auto and home policies are exceeded. Going to $5M costs about $683 a year, less than double the price of the first million for 5x the coverage.
We’ve all looked at classic physicians personal finance checklists. Every one lists the same basic things. Max the 401(k). Buy own-occupation disability insurance. Do the backdoor Roth. Few of them mention the product we think is one of the most overlooked lines of asset protection: Umbrella insurance. This niche tool often gets left by the wayside but should be considered as our society is becoming more litigious and, in our view, a visible physician income makes you a more attractive defendant.
What an umbrella policy is
An umbrella policy is personal liability coverage that sits on top of your auto and homeowners insurance (hence “umbrella”). When a claim blows past the limits of your other insurance policies, the umbrella pays. Size is typically $1 million to $5 million of additional coverage, and it often pays your legal defense costs on top of the limit. In our view, insurance should only be used to protect against the extreme downside scenario, and an umbrella policy is the purest version of that idea. Here is the full insurance stack a physician needs, and where the umbrella sits. (Notice whole and variable life insurance don’t make the list!)
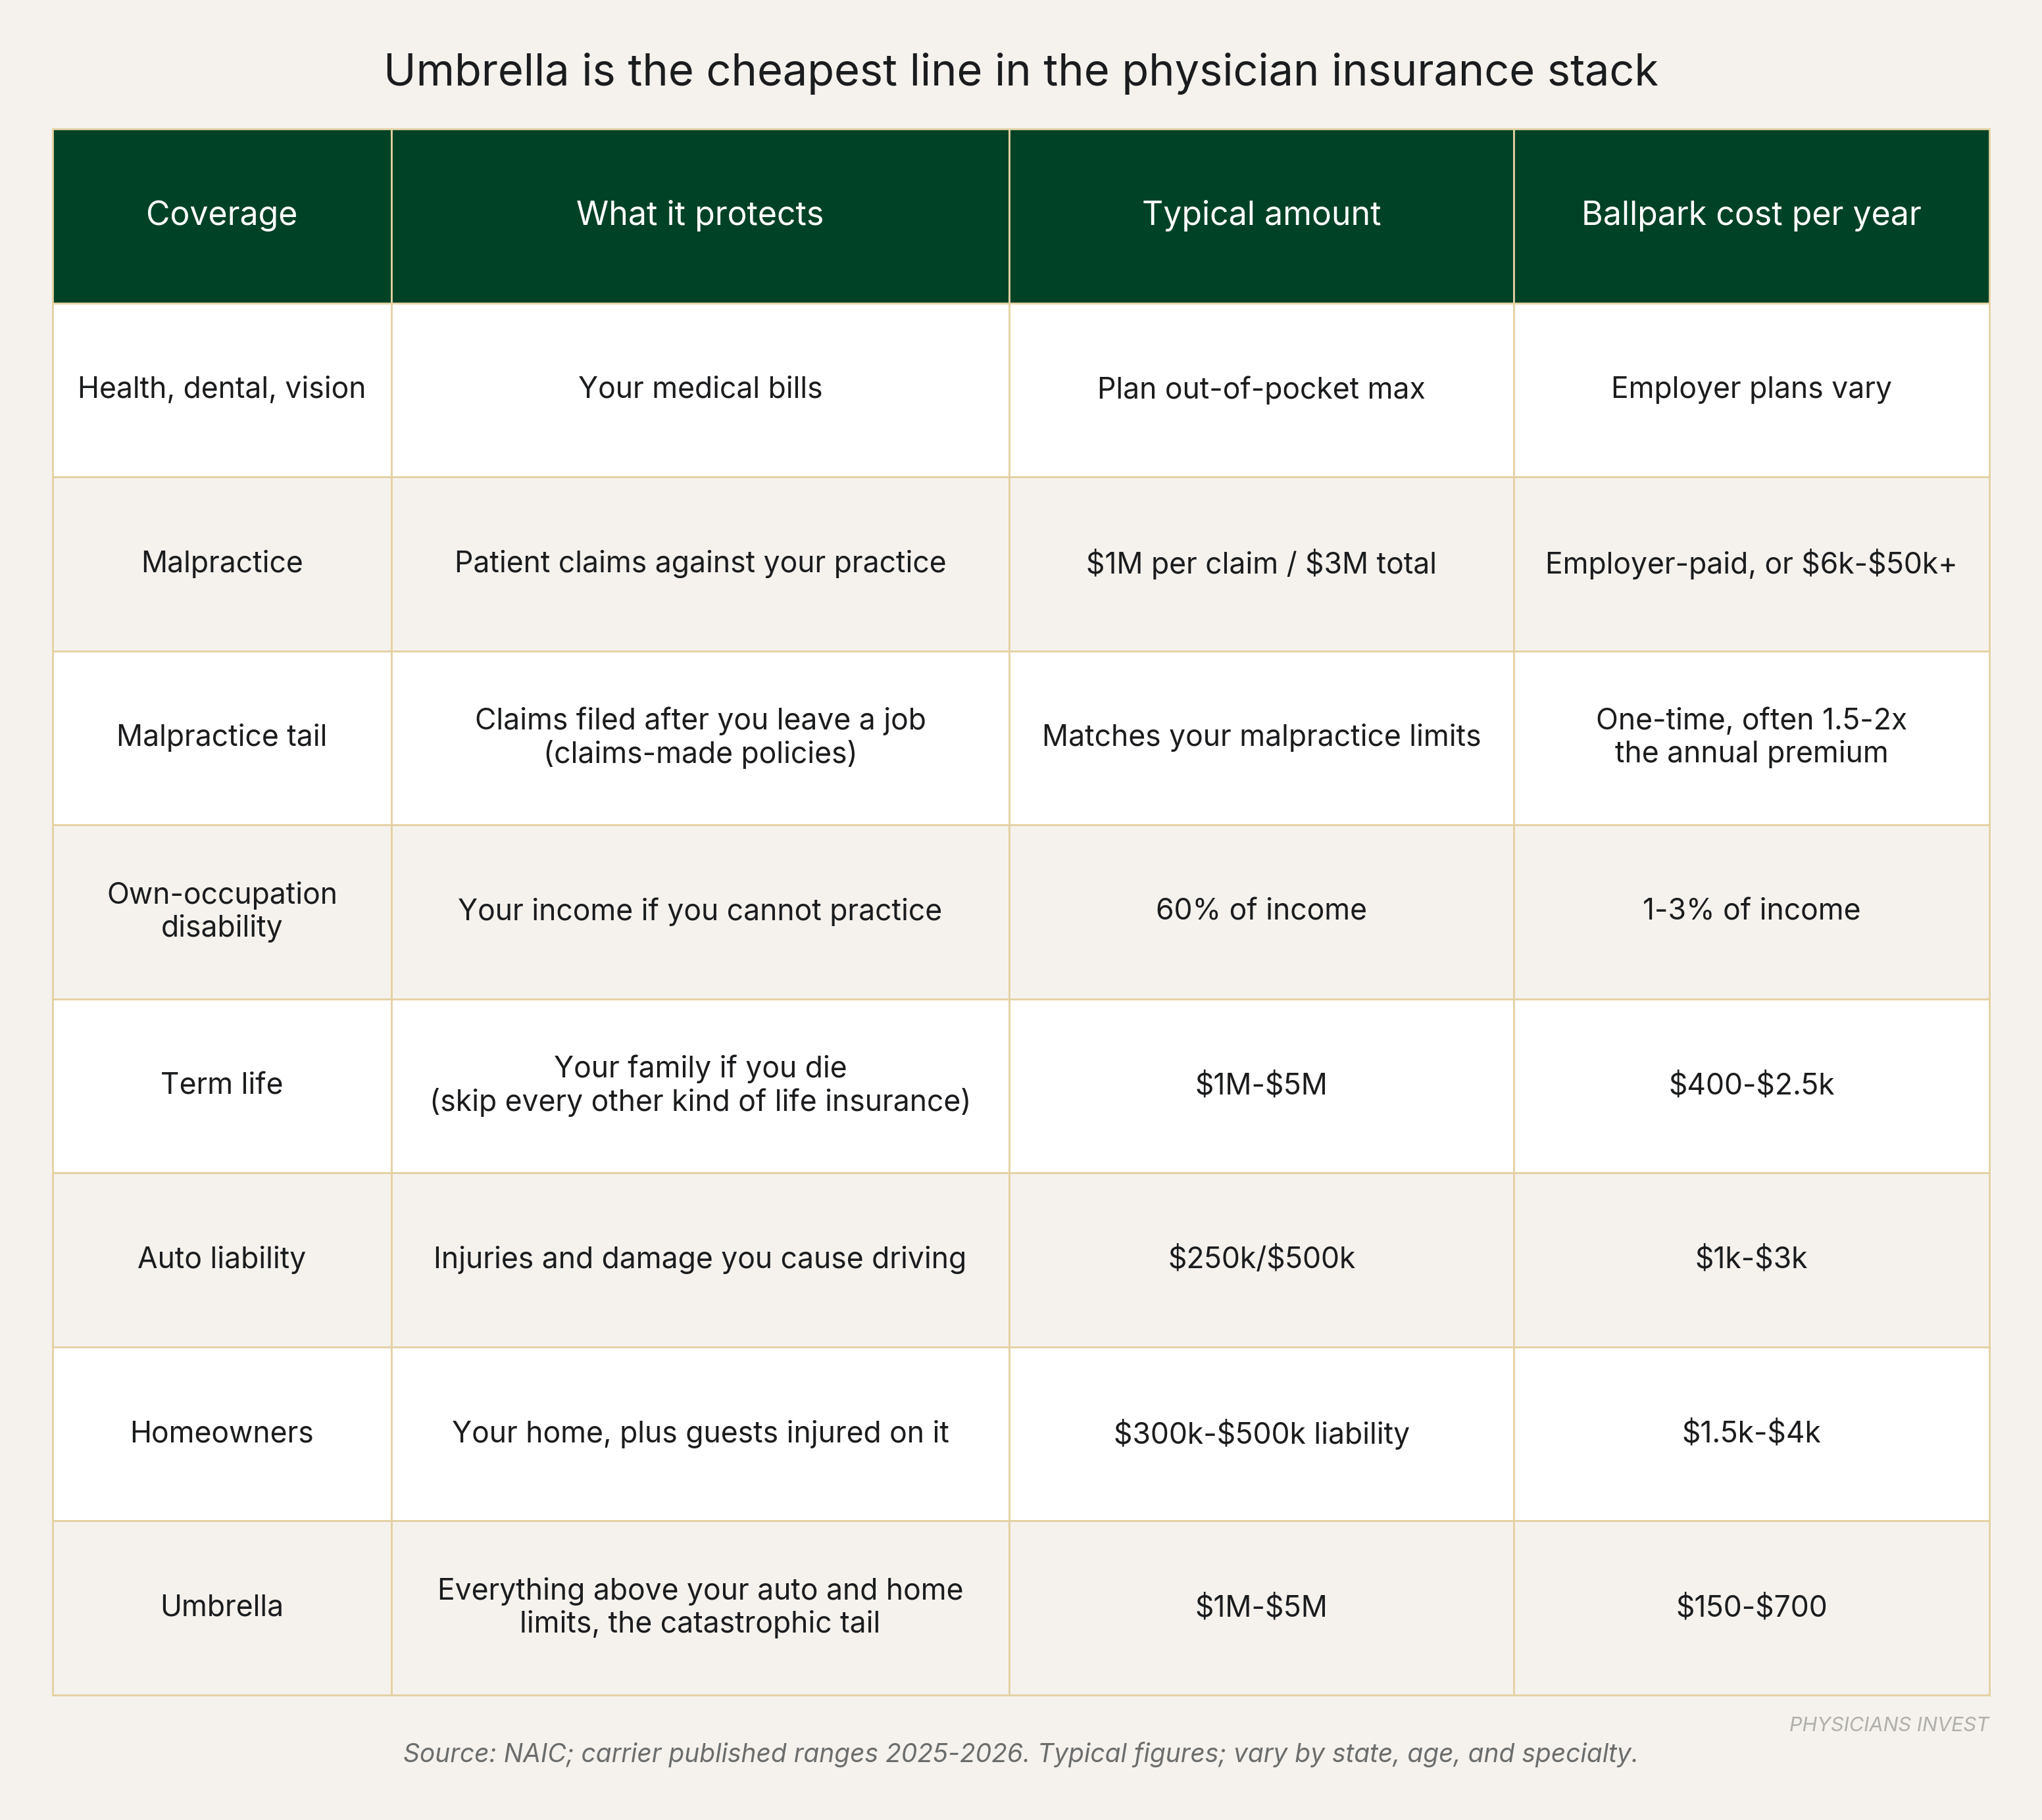
Two things jump out of that table: umbrella is the cheapest line on it, and it carries some of the largest payout sizes on the list.
One note: carriers require underlying limits first, typically $250k/$500k on auto and $300k on home liability, so the true cost of an umbrella includes raising those primaries if they are below those levels currently.
The lawsuit tail is growing
A “nuclear verdict” is legal-industry shorthand for a jury award over $10 million. They used to be rare and unfortunately, as our society has decided that everything deserves a lawsuit, they aren’t anymore.
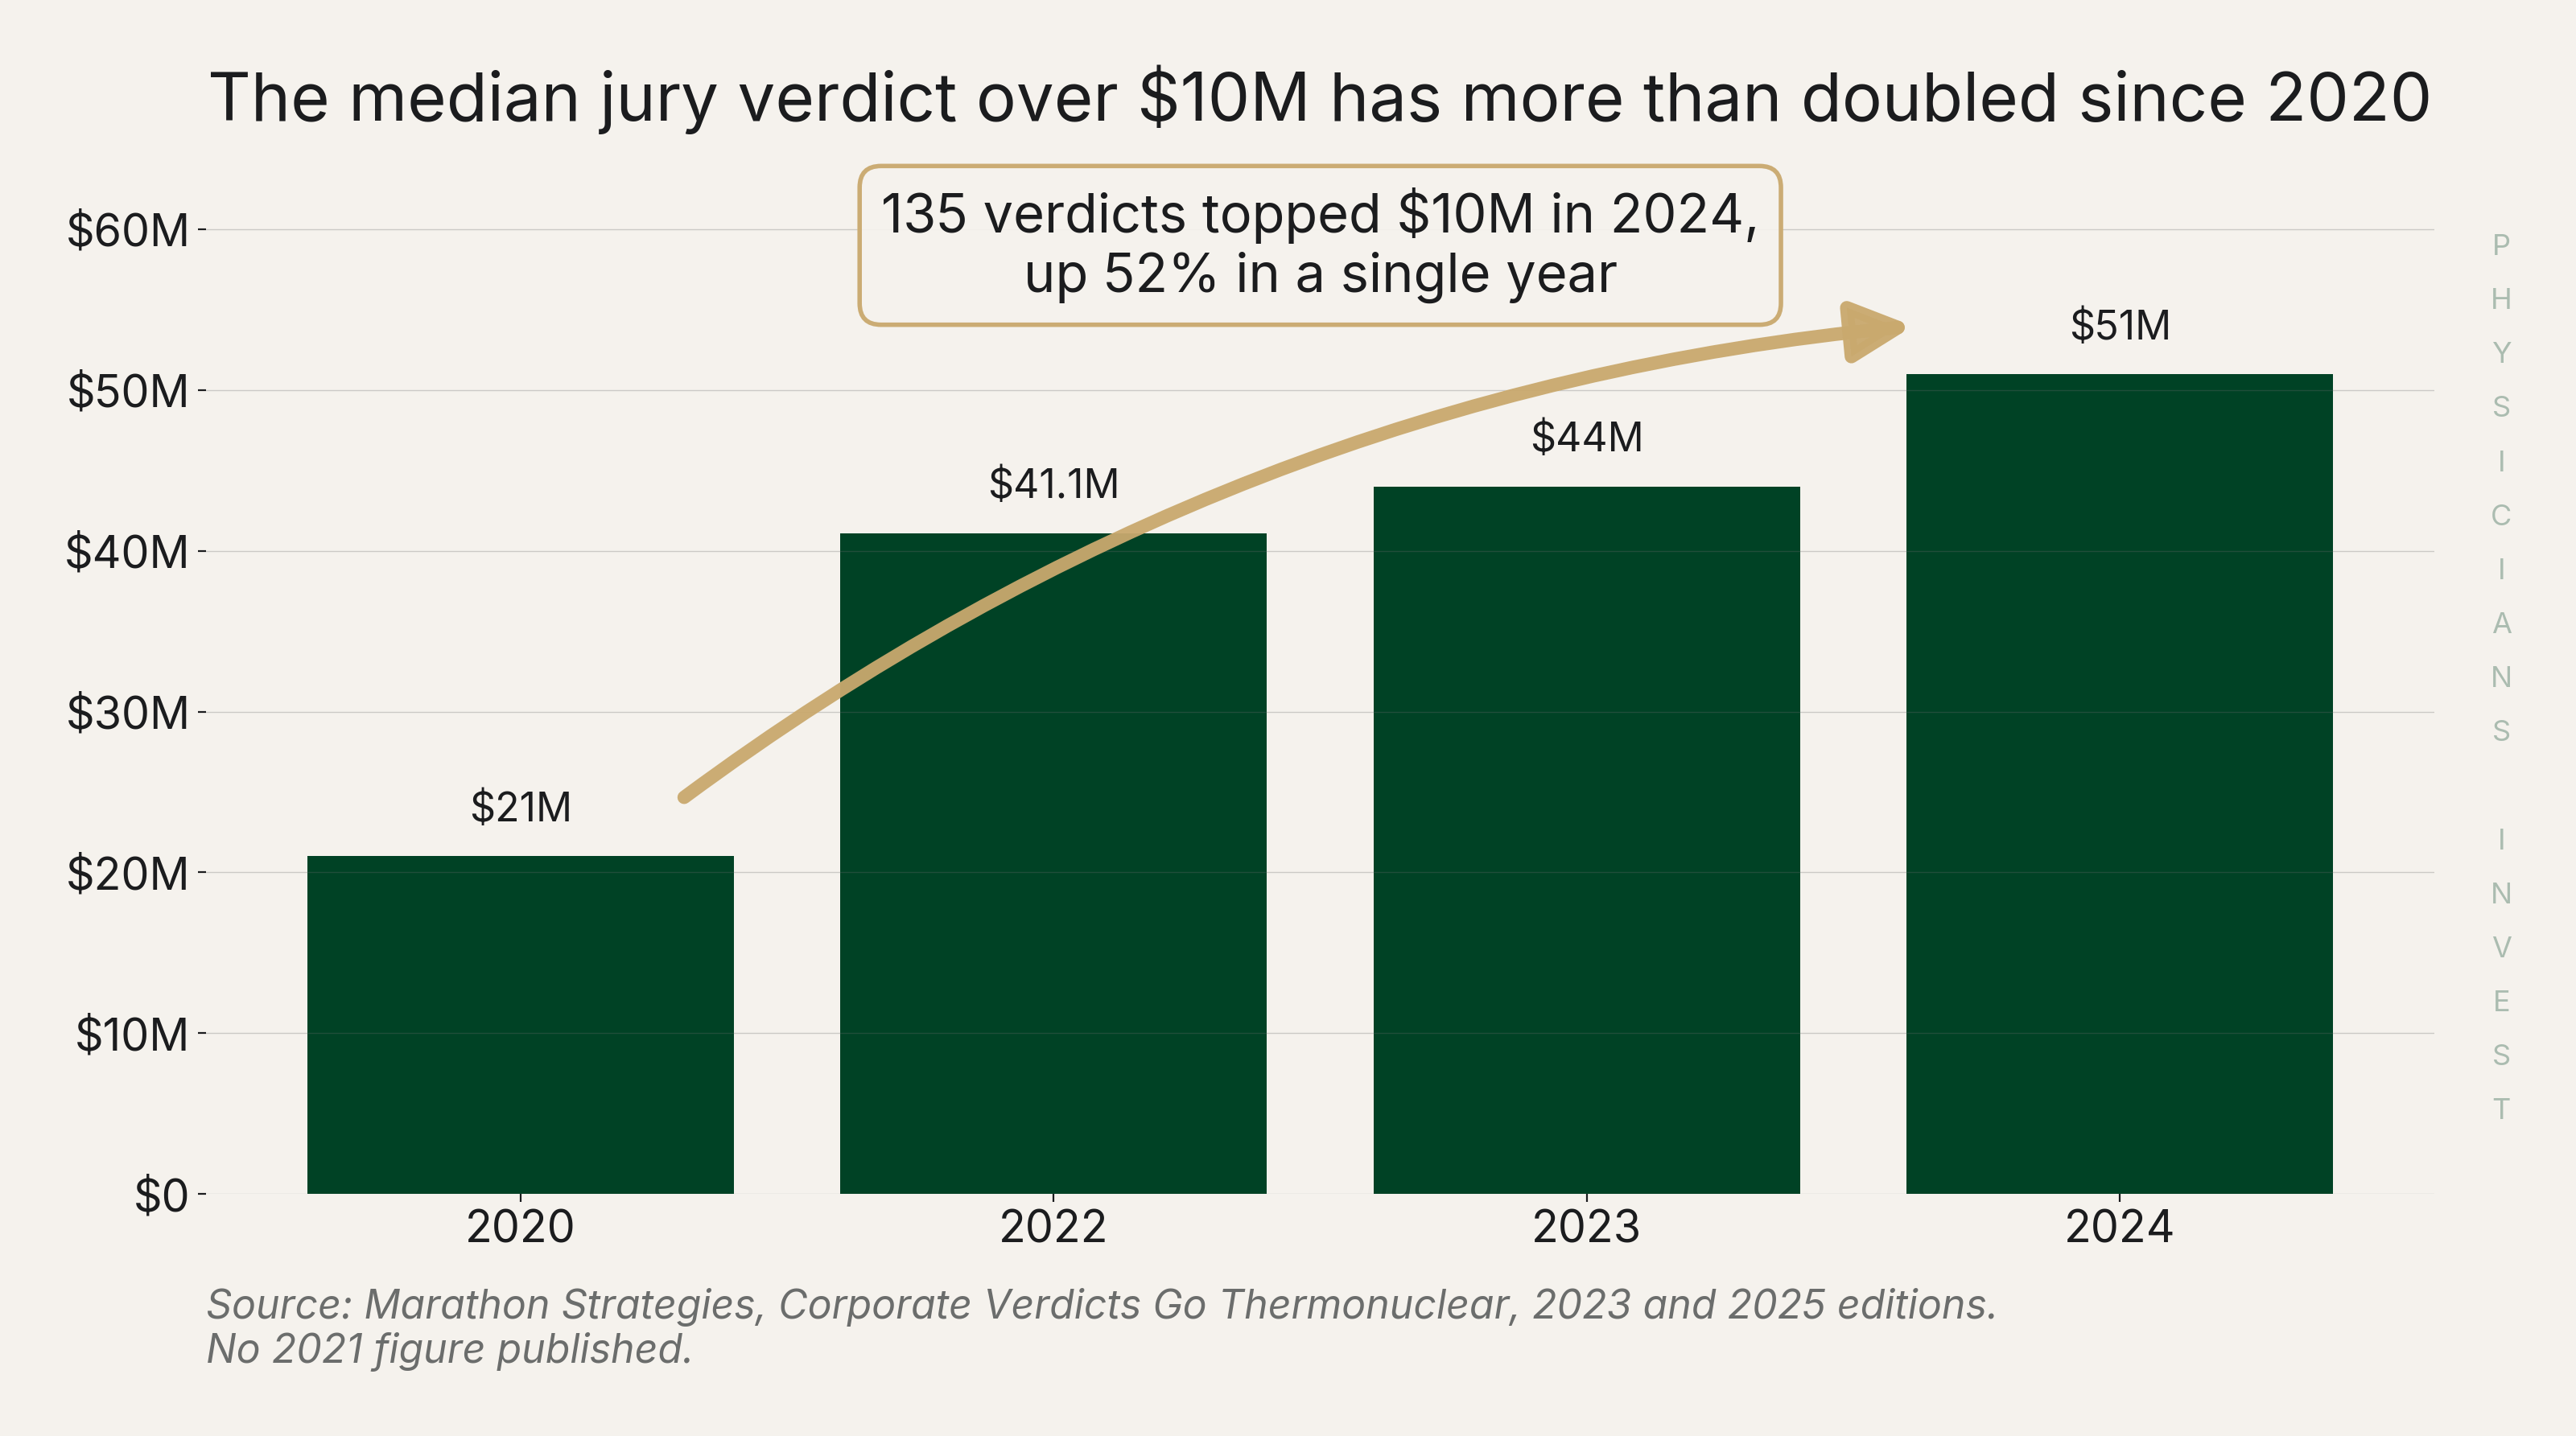
The median verdict over $10 million has more than doubled since 2020. Liability claims overall rose 57% over the past decade, significantly more than inflation. Carriers are reacting: underlying-limit requirements are climbing, and the big umbrellas are getting harder to buy.
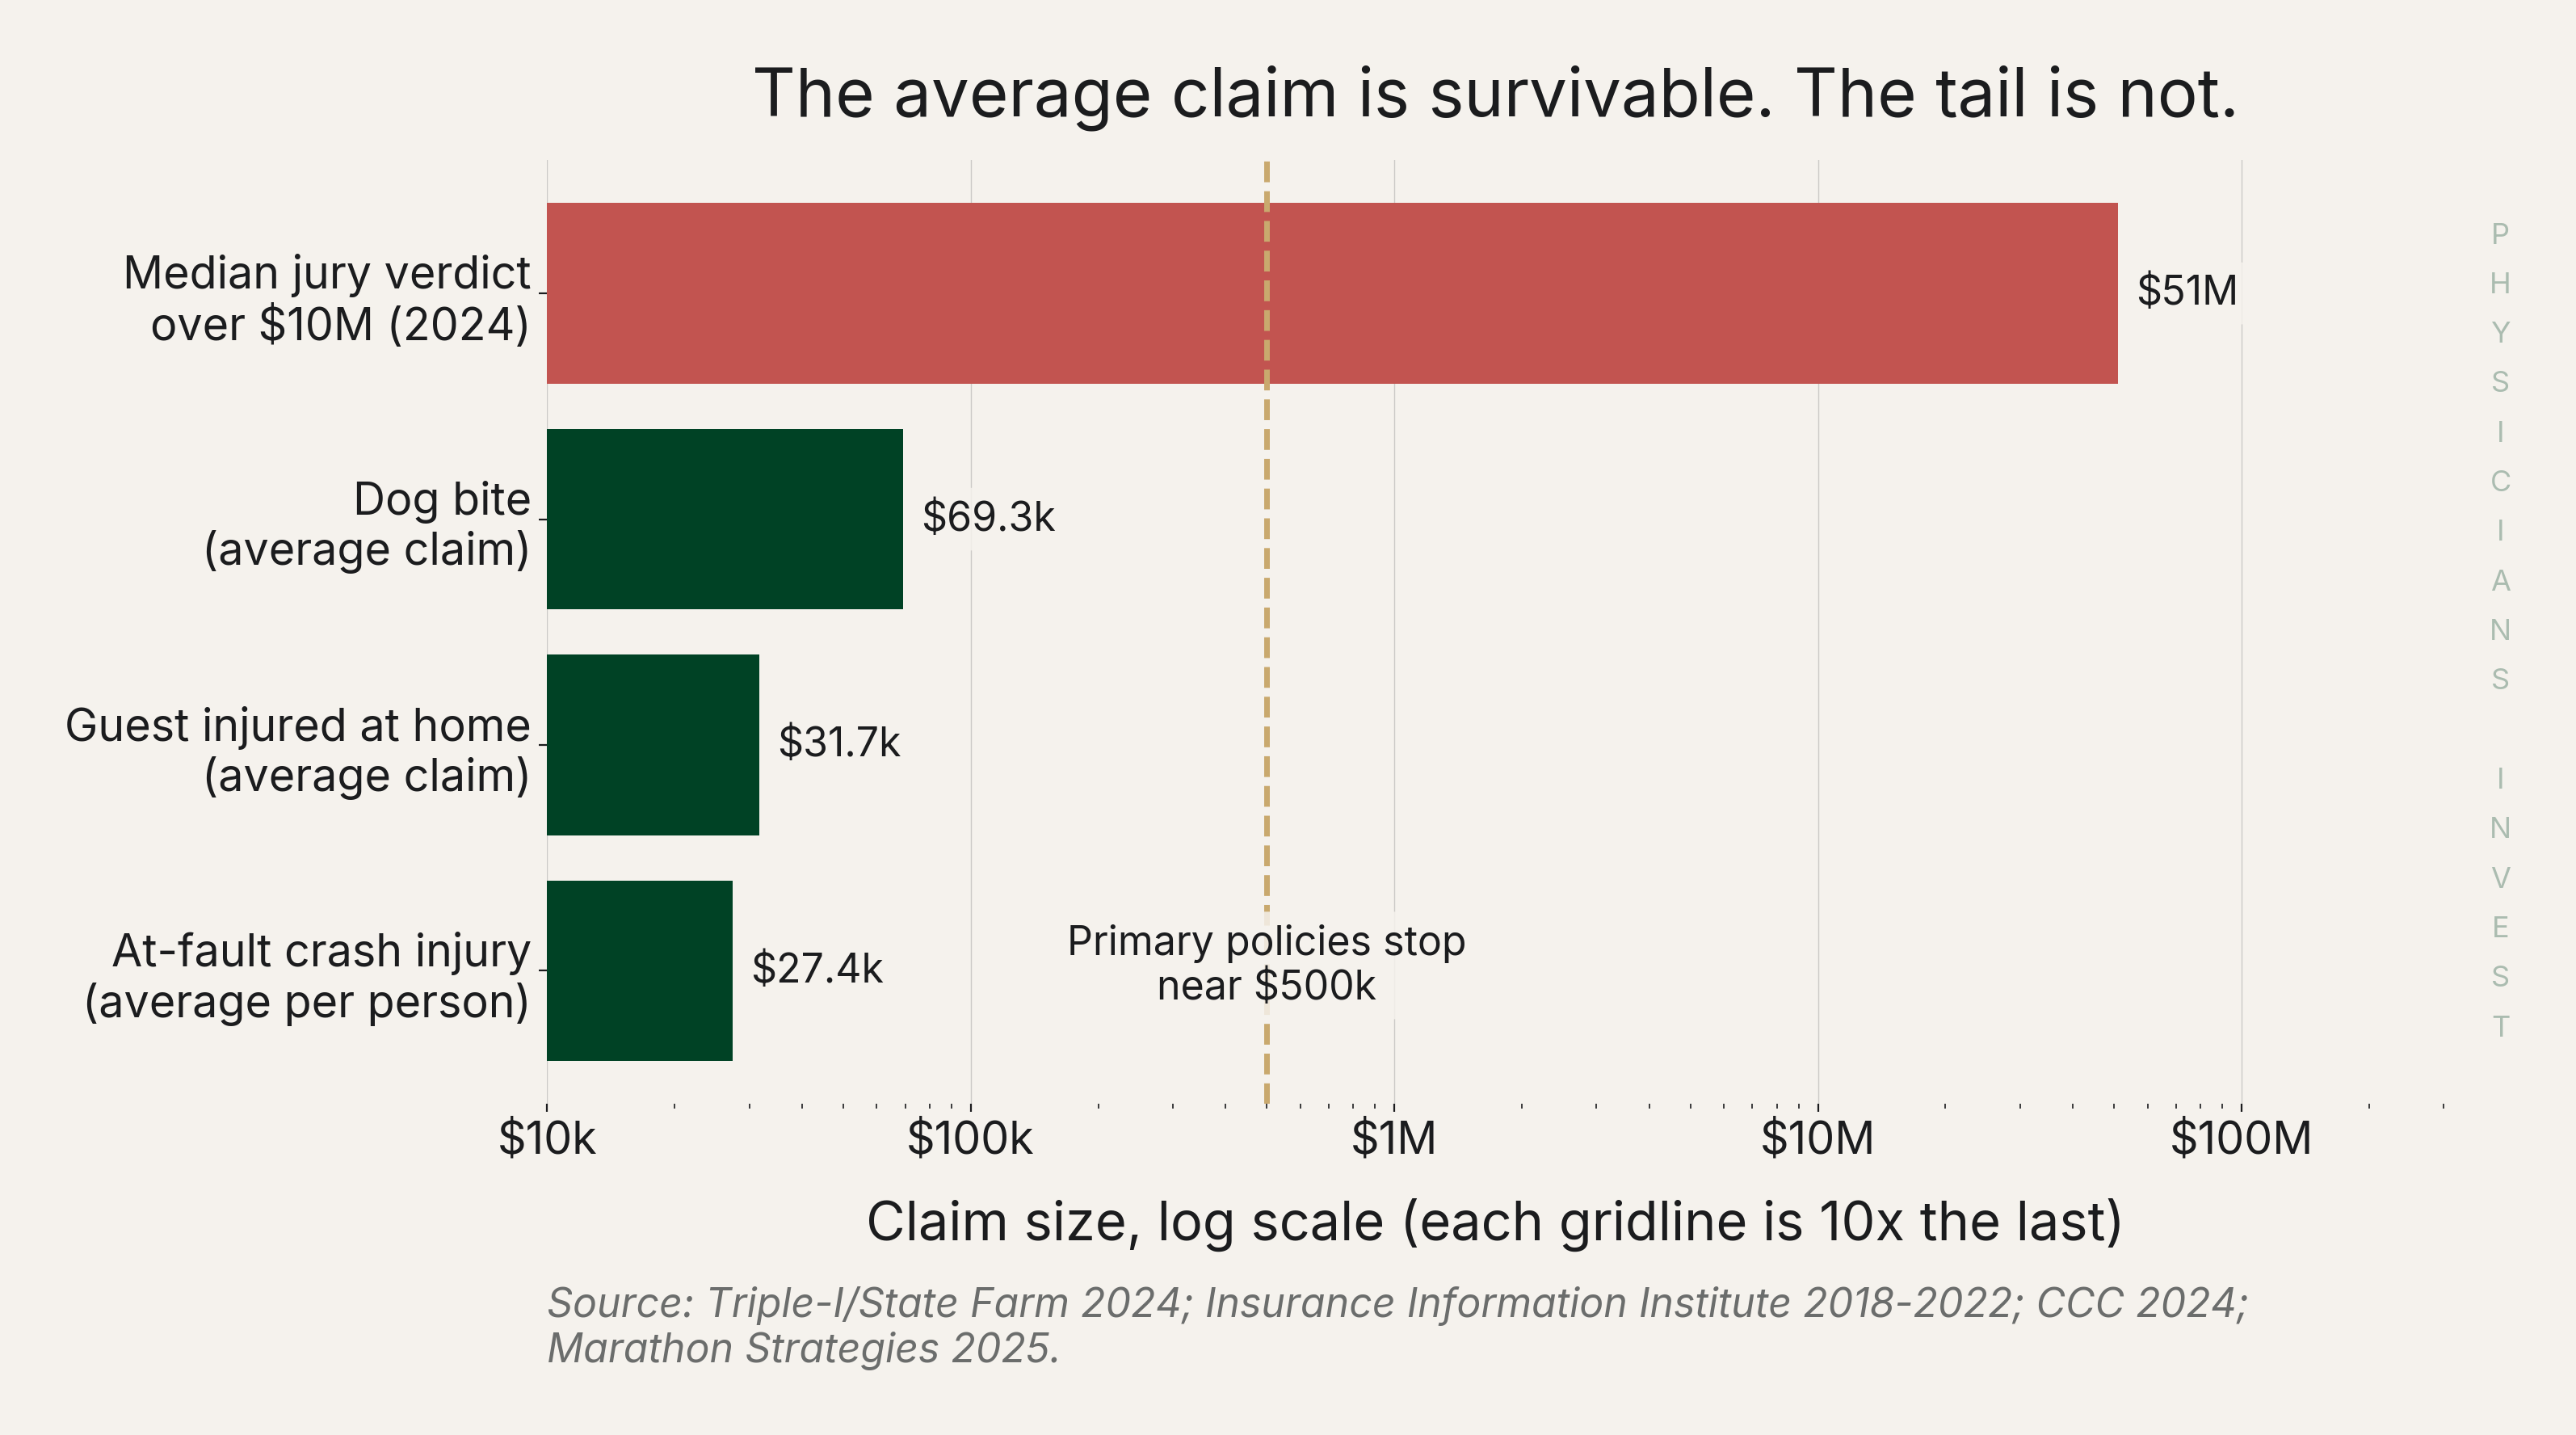
Everything left of the gold line is survivable, either out of pocket or within your policy. The red bar is not survivable. Most physicians will not see a “nuclear verdict.” But claim sizes are climbing toward the ceiling on standard home and auto policies, and that ceiling needs protection above it to survive a tail event.
Umbrella covers your personal life, not your professional life
Here’s the map of what is covered by umbrella insurance and what is not.
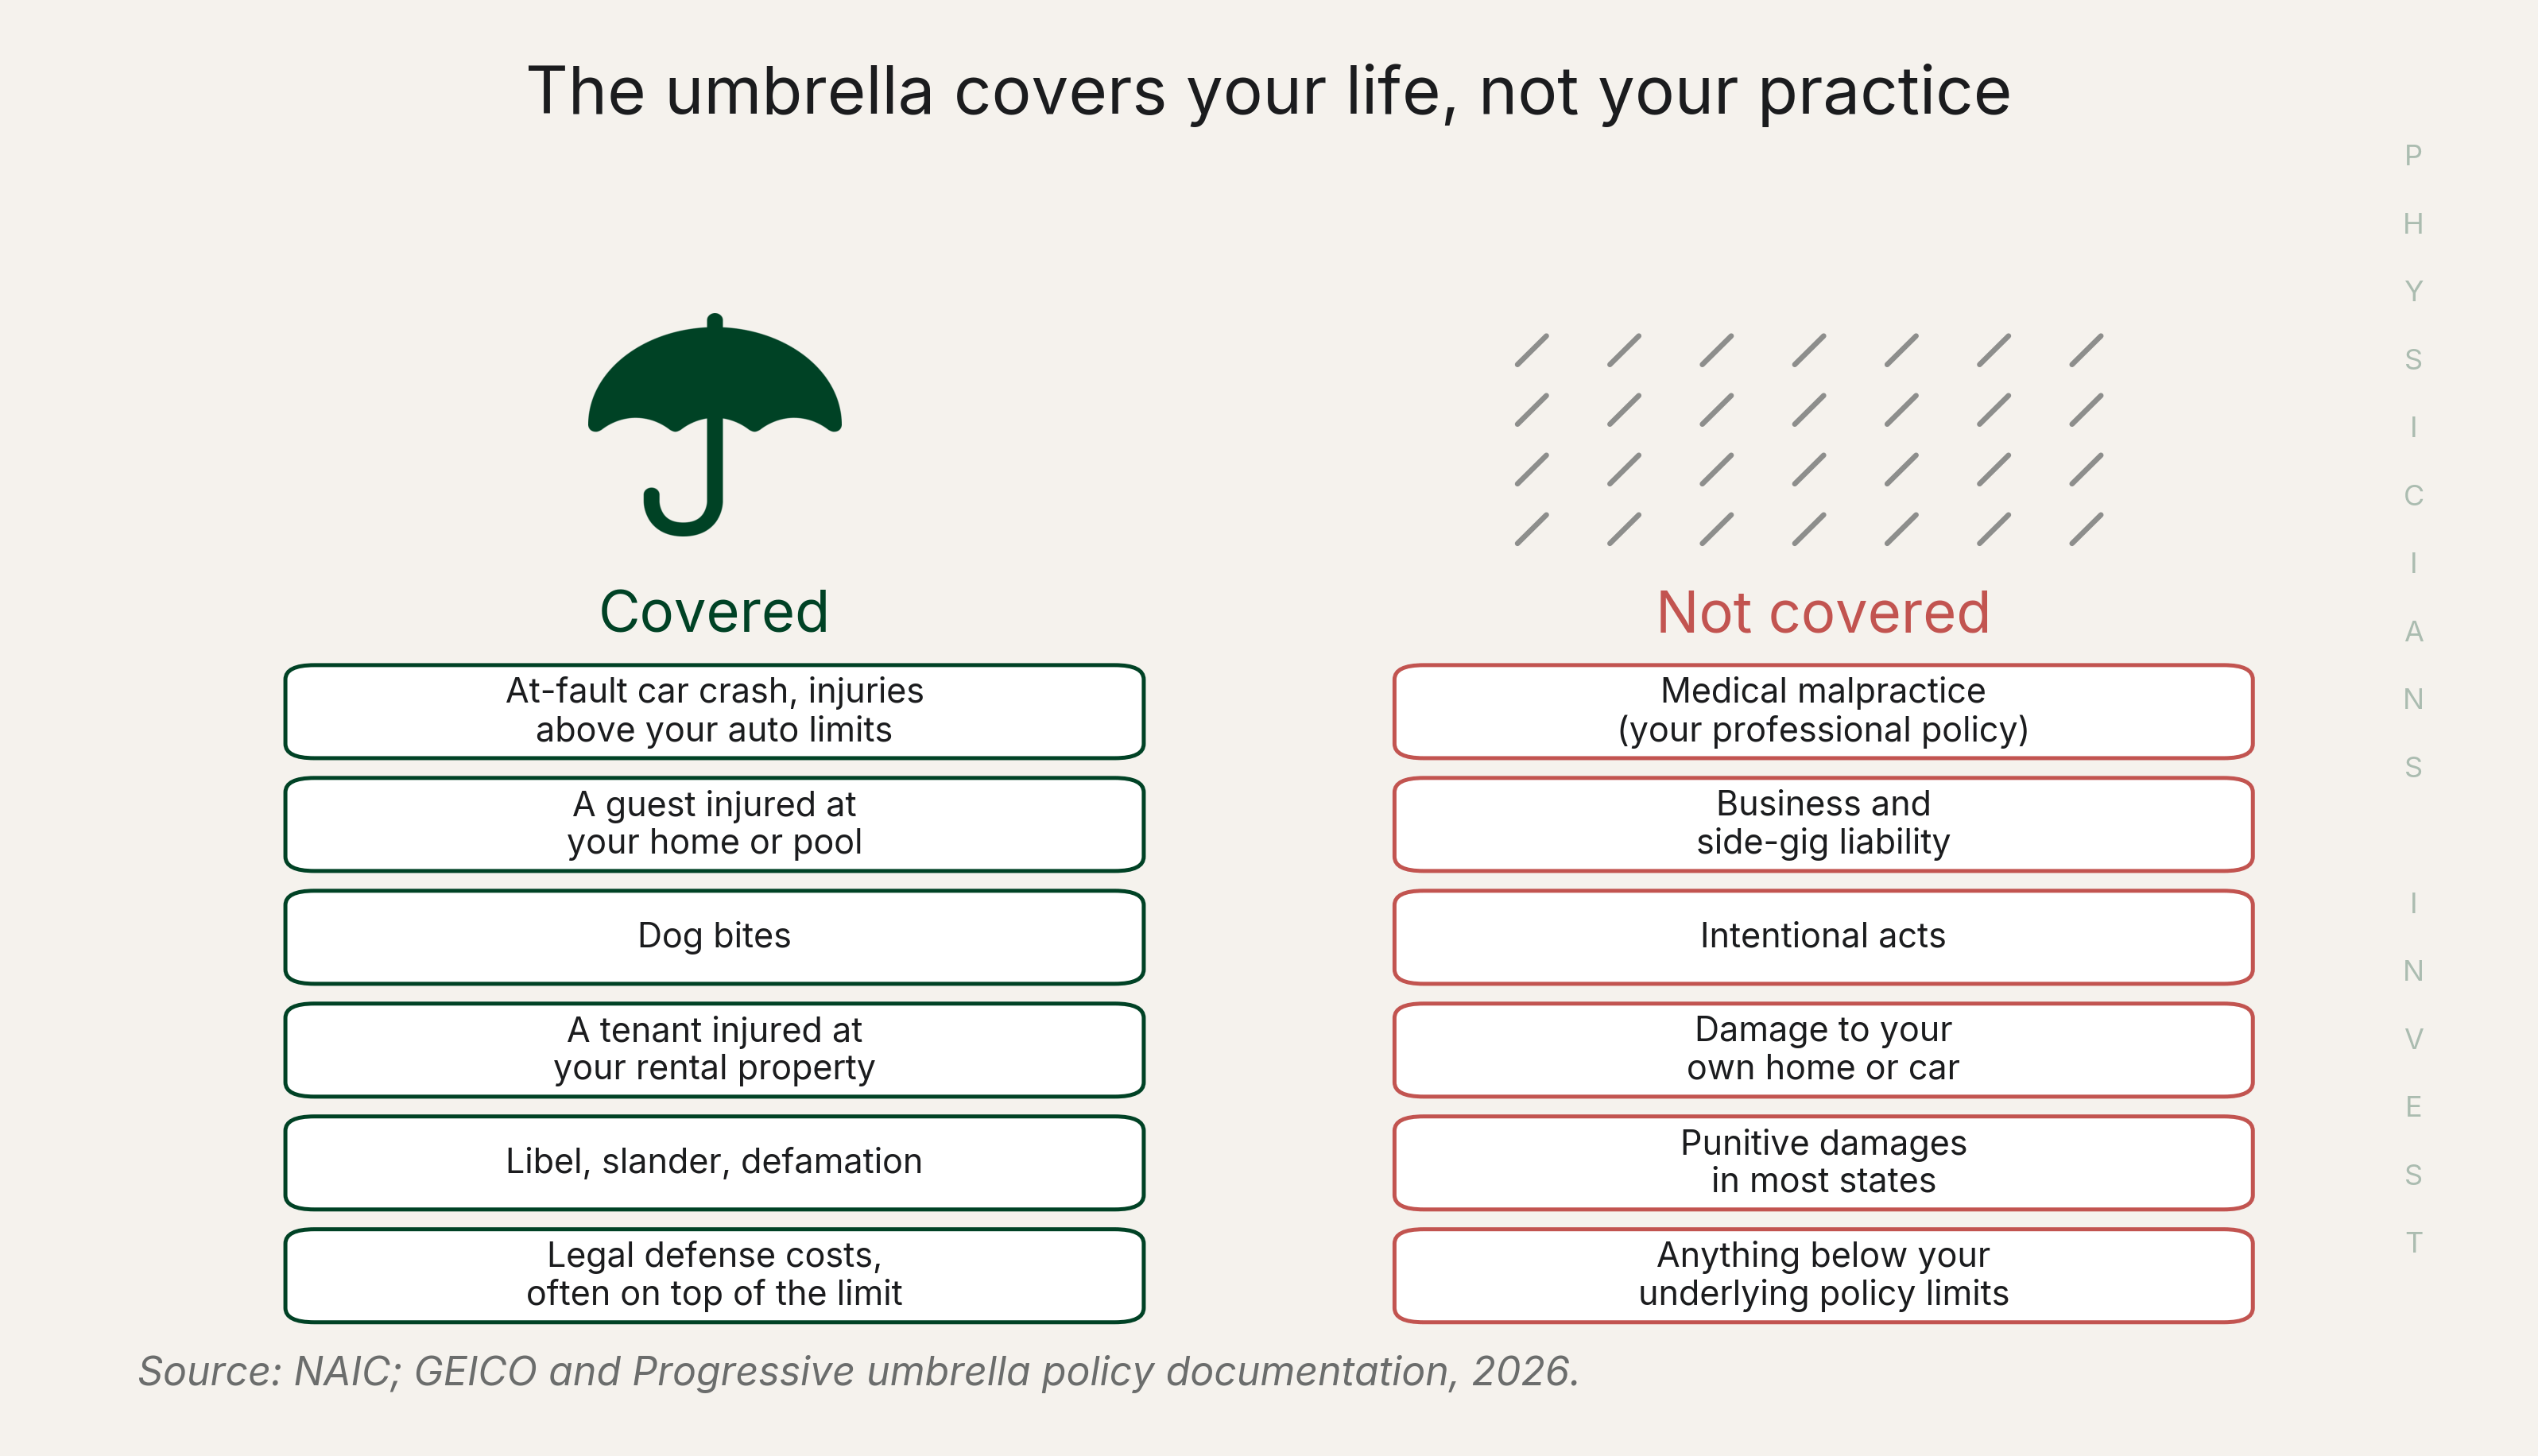
Malpractice is not covered by any umbrella policy but fortunately, malpractice claims almost never reach personal assets. In the most complete study of closed malpractice claims, physicians paid out of pocket in only roughly 0.5% of cases. Plaintiffs’ lawyers chase the money, and therefore go after the insurance company rather than the individual because insurance company assets are a much bigger carrot than the physician’s.
The umbrella exists to protect the personal side of your life from claims associated with common parts of physician lives. Examples:
The teen driver
The pool
The dog
The rental property
The non-profit board seat
Cheap cost, but extensive coverage
So what does umbrella insurance cost?
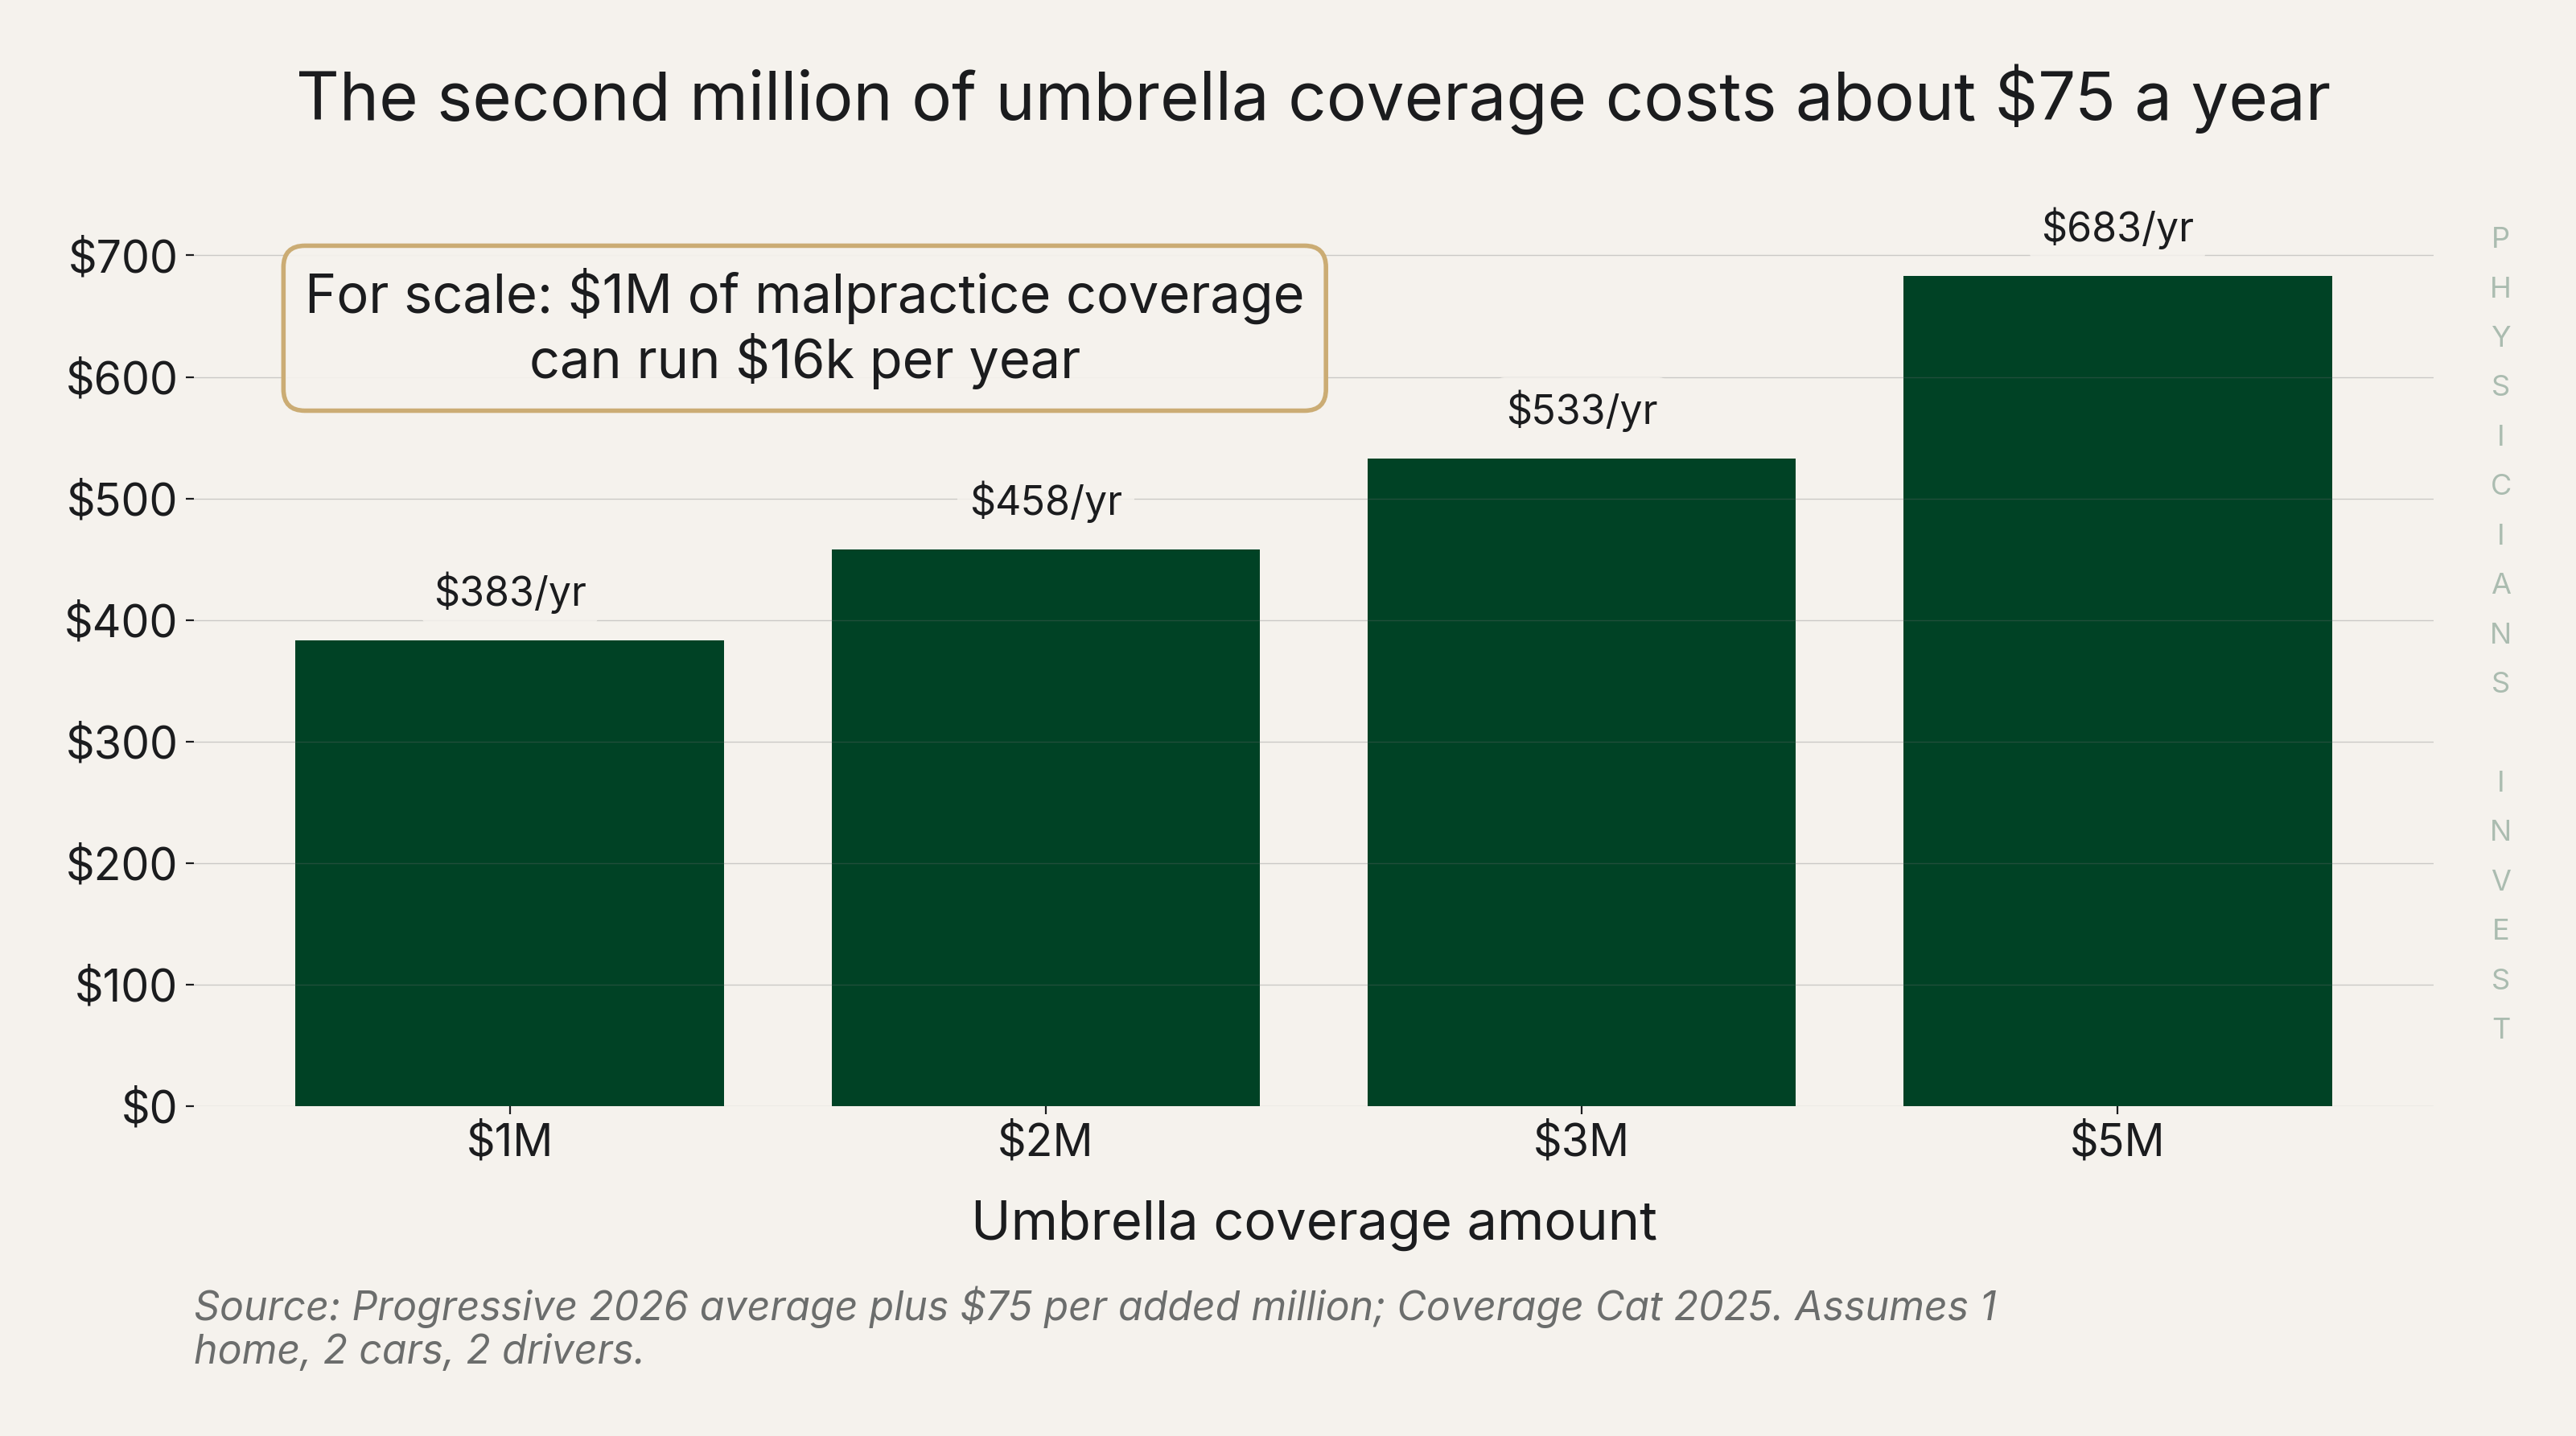
The first million is the most expensive at about $400/yr. The second million costs about $75/yr. The third, even less than that. For scale, $1 million of malpractice coverage can run $16,000/yr.
The reason it’s cheap is because claims don’t come in that often. About 1 in 1,100 homeowners policies see a liability claim in a given year, and only a fraction of those reach the umbrella layer. You’re paying option money to protect from an unlikely catastrophe. Think of umbrella insurance like the crash cart in your department. Cheap to stock, rarely touched, and the only thing that matters in the one moment it’s needed.
The Move
Before picking a number, it’s important to know what a judgment can and cannot take.
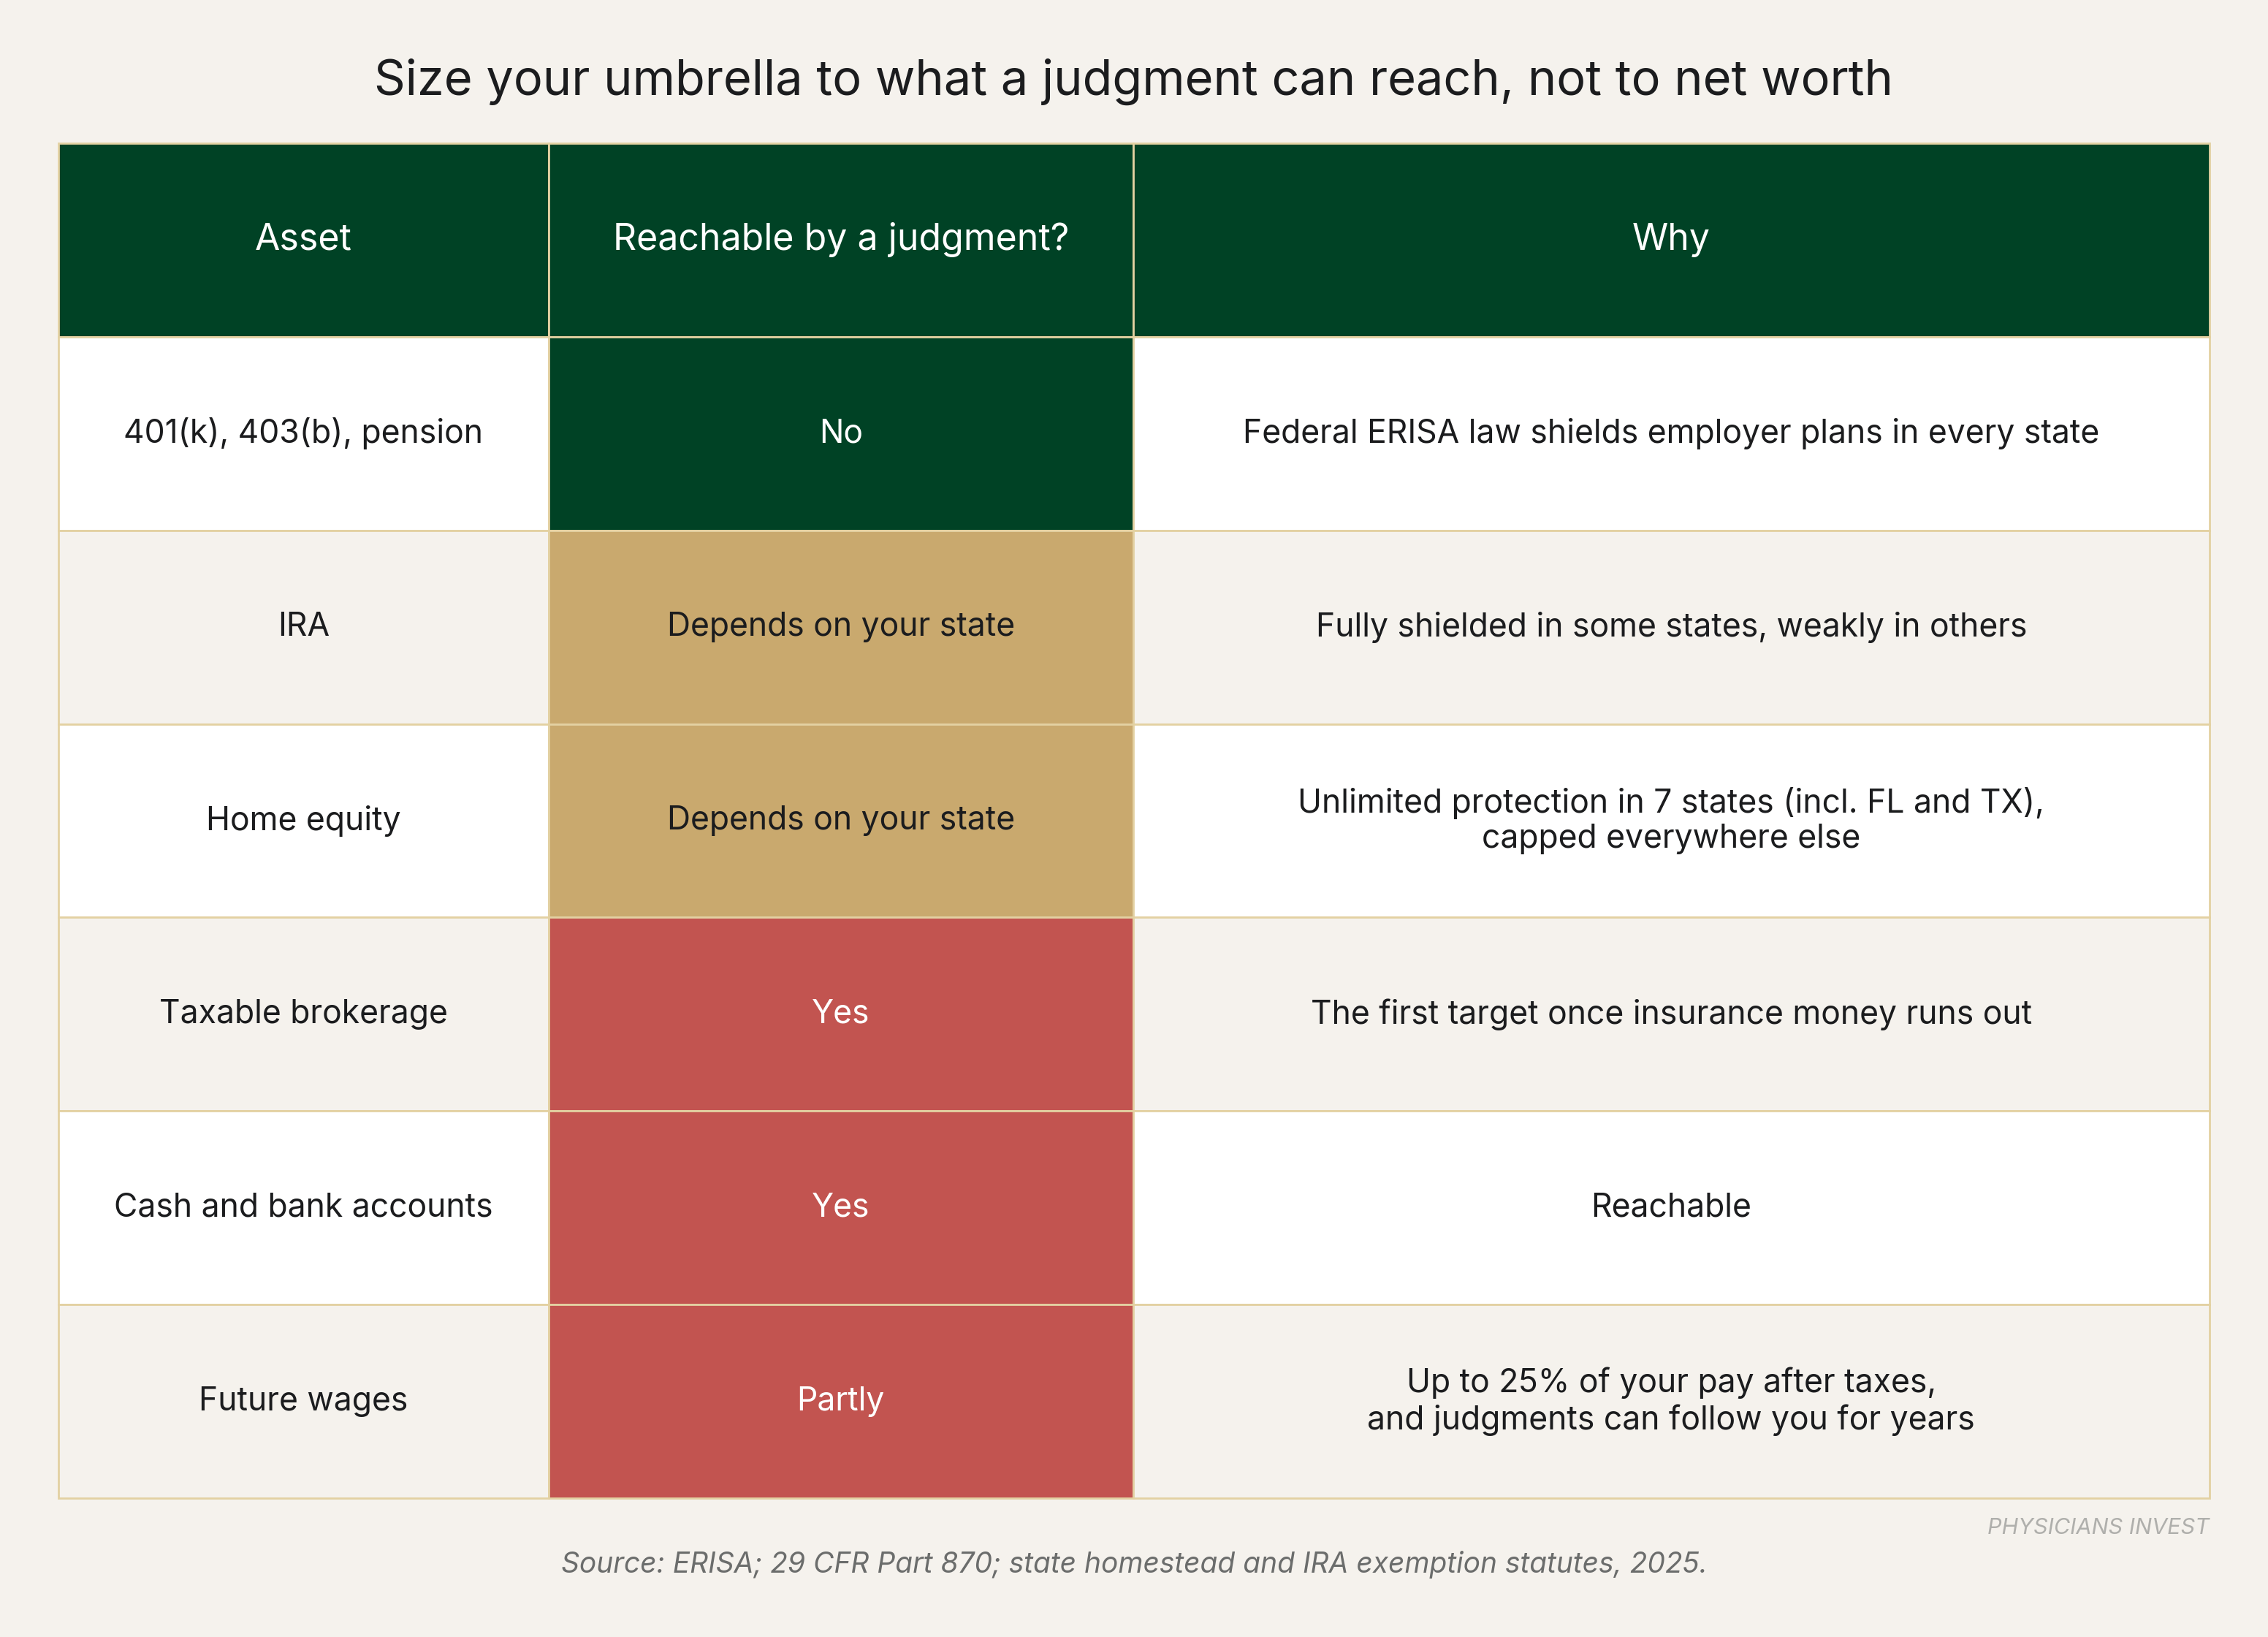
Your employer 401(k) is untouchable. Your brokerage account, home equity above your state’s shield, and up to 25% of your after-tax pay are not. That exposed pool and not your gross net worth, is what you’re insuring. Here’s our suggested framework:
Earning an attending income? Your income is the exposed asset, even with minimal net worth if carrying significant student debt. Most physicians in this group start at $1M, about $400/year.
Exposed assets above ~$500k? This includes taxable brokerage plus home equity above your state’s exemption as well as other personal assets not shielded. The exposed pile is what the policy should be sized to. The extra millions cost ~$75 each.
Teen driver, pool, rental property, or board seat? These are the classic umbrella triggers, and households with them typically carry a tier more.
Resident with negative net worth and none of the above? Waiting to purchase until you have an attending salary is defensible.
Where to buy? Quote it through your current auto and home carrier first (multi-policy discounts can be significant and it simplifies life all being under one provider), expect to raise your underlying limits if you’ve kept them low, and buy the size you need based on the list above. One more last thing: buy the size you’ll want in five years. Raising the limit later can mean a full new underwriting process.
Not sure what a judgment could reach in your state, or how big your umbrella should be? Book a free consultation.
Sources
Data
Marathon Strategies, Corporate Verdicts Go Thermonuclear (2025 edition) -- nuclear verdict counts and the median $10M+ verdict trend since 2020
Swiss Re sigma 4/2024, litigation costs and claims inflation -- the 57% rise in US liability claims over the past decade
Insurance Information Institute, Facts + Statistics: Homeowners and Renters Insurance -- 1-in-1,100 homeowners liability claim frequency
Progressive, How Much Does Umbrella Insurance Cost? -- first-million umbrella pricing (~$400/yr) and per-million marginal cost
Coverage Cat, Required Underlying Limits for Personal Umbrella Policies -- standard 250/500 auto and $300K home underlying-limit requirements
Academic
Silver, Hyman, Black & Paik, “Policy Limits, Payouts, and Blood Money,” UC Irvine Law Review -- closed malpractice claims study showing ~0.5% out-of-pocket physician payments
Physician-Specific
White Coat Investor, How Much Umbrella Insurance Do You Need -- the $16,000/yr malpractice premium vs. umbrella cost comparison
Policy
eCFR, 29 CFR Part 870 -- Restriction on Garnishment -- federal 25%-of-disposable-earnings wage garnishment cap
Alper Law, How to Protect Retirement Accounts from Creditors and Lawsuits -- ERISA-qualified plan (401(k)) creditor protection
Related from Physicians Invest